In this article, let’s see how you can improve your DSCR ratio: In our previous article, “DSCR Loans 101: A Complete Guide for First-Time Real Estate Investors,” we explained how Debt Service Coverage Ratio loans enable investors to qualify for financing based on their property’s income rather than personal earnings. As we discussed, most lenders require a minimum DSCR of 1.0, with many preferring 1.25 or higher for optimal terms.
But what happens when your property’s DSCR falls short of these requirements? The good news is that your debt service coverage ratio isn’t fixed—there are concrete steps you can take to improve it. This article outlines seven proven strategies to boost your DSCR and qualify for better loan terms on your investment properties.
Understanding DSCR: A Quick Refresher
Before diving into improvement strategies, let’s quickly review what DSCR means:
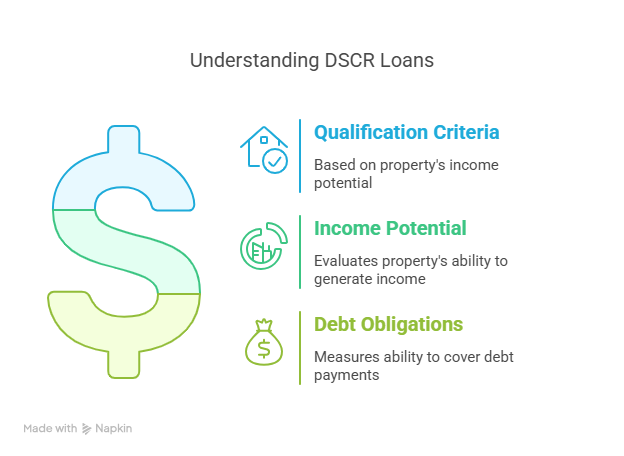
DSCR = Monthly Rental Income ÷ Monthly PITIAWhere PITIA represents Principal, Interest, Taxes, Insurance, and Association dues.
A higher DSCR indicates a property with stronger cash flow relative to its debt obligations. Lenders view this as lower risk, potentially qualifying you for better interest rates, higher LTV ratios, and more favorable loan terms overall.
Strategy 1: Increase Rental Income
The most direct way to improve your DSCR ratio is to boost the numerator in the equation—your rental income.
Actionable steps:
- Conduct market research: Compare similar rentals in your area to ensure you’re charging competitive rates
- Make strategic upgrades: Focus on improvements with high ROI like fresh paint, updated flooring, or new appliances
- Add value-generating amenities: Consider offering furnished options, pet-friendly policies, or including utilities (with appropriate rent increases)
- Optimize short-term rental potential: If zoning allows, explore whether your property could generate higher income as a vacation rental
Even a modest 5-10{b92bc4f90207b85c6e672c12389678840946188ba238ac1c1570ae4bcd8b3d52} increase in rental income can significantly impact your DSCR. For a property with $2,000 monthly expenses and $2,000 in rent (DSCR of 1.0), increasing rent to $2,200 improves the DSCR to 1.1—potentially opening doors to better financing options.
Strategy 2: Refinance to Lower Interest Rates
If you’re calculating DSCR for a refinance, securing a lower interest rate can dramatically improve your ratio by reducing your monthly payment.
Actionable steps:
- Shop multiple lenders: Different DSCR loan providers offer varying rates and terms
- Improve your credit score: As we mentioned in our previous article on DSCR loans, better credit can lead to lower rates
- Consider longer amortization periods: Moving from a 15-year to a 30-year term reduces monthly payments
- Time your refinance strategically: Watch market trends and lock in rates during favorable cycles
A 1{b92bc4f90207b85c6e672c12389678840946188ba238ac1c1570ae4bcd8b3d52} reduction in interest rate on a $300,000 loan can lower monthly payments by approximately $167-250, potentially improving your DSCR by 0.05-0.15 depending on your property’s income.
Strategy 3: Reduce Property Taxes
Property taxes are often a significant expense for investment properties and directly affect your DSCR calculation.
Actionable steps:
- Appeal your assessment: If your property is overvalued, file an appeal with your local tax assessor
- Research comparable properties: Gather evidence of similar properties with lower assessments
- Apply for available exemptions: Some jurisdictions offer investment property tax breaks
- Plan purchases with tax considerations: When buying new properties, factor in tax rates across different areas
Successful tax appeals can reduce annual expenses by hundreds or thousands of dollars, directly improving your DSCR ratio.
Strategy 4: Optimize Insurance Costs
Insurance is another expense that factors into your DSCR calculation that can often be optimized.
Actionable steps:
- Shop multiple carriers: Get quotes from at least 3-5 insurance providers
- Bundle policies: Combine multiple properties under one carrier for potential discounts
- Increase deductibles strategically: Higher deductibles mean lower premiums
- Install safety features: Security systems, smoke detectors, and weather protection can reduce premiums
Even saving $30-50 monthly on insurance contributes to improve your DSCR ratio without affecting rental income.
Strategy 5: Reduce or Eliminate HOA Fees
For properties in associations, HOA fees directly impact your DSCR calculation.
Actionable steps:
- Consider properties without HOAs: When acquiring new properties, factor HOA costs into your DSCR projections
- Get involved in the HOA board: Help manage costs and prevent unnecessary fee increases
- Evaluate HOA services: Determine if amenities justify costs or if a different property might offer better DSCR potential
- Research fee reduction options: Some HOAs offer hardship programs or payment plans
While you may have limited ability to reduce existing HOA fees, understanding their impact helps with future investment decisions.
Strategy 6: Increase Your Down Payment
Sometimes the most effective way to improve DSCR is simply to borrow less. As we noted in our DSCR Loans 101 guide, lenders typically require 20-25{b92bc4f90207b85c6e672c12389678840946188ba238ac1c1570ae4bcd8b3d52} down, but going beyond this minimum can dramatically improve your ratio.
Actionable steps:
- Calculate optimal loan amounts: Run scenarios with different down payments to find DSCR sweet spots
- Consider delayed gratification: Instead of purchasing immediately, save for a larger down payment
- Explore creative funding sources: Partner with investors or use portfolio lines of credit
- Evaluate cash-on-cash returns: Balance the DSCR improvement against your overall investment returns
For example, increasing your down payment from 20{b92bc4f90207b85c6e672c12389678840946188ba238ac1c1570ae4bcd8b3d52} to 30{b92bc4f90207b85c6e672c12389678840946188ba238ac1c1570ae4bcd8b3d52} on a $400,000 property reduces your loan by $40,000, potentially improving your DSCR by 0.1-0.2 points.
Strategy 7: Bundle Multiple Properties
Some DSCR lenders will consider the aggregate performance of multiple properties when qualifying borrowers for portfolio loans.
Actionable steps:
- Combine high and low-performing properties: Use stronger properties to offset weaker ones
- Explore portfolio financing options: Ask lenders about their blanket loan or cross-collateralization policies
- Strategically time acquisitions: Consider purchasing high-DSCR properties before applying for financing on borderline deals
- Work with portfolio loan specialists: Find lenders experienced with multiple-property financing
This approach can be particularly effective when one property has exceptional cash flow while another has strong appreciation potential but lower current income.
Putting It All Together: Improve Your DSCR Ratio Case Study
Let’s examine how these strategies might work in combination:
Starting Scenario:
- Property Value: $400,000
- Loan Amount (75{b92bc4f90207b85c6e672c12389678840946188ba238ac1c1570ae4bcd8b3d52} LTV): $300,000
- Monthly PITIA: $2,400
- Monthly Rental Income: $2,400
- Initial DSCR: 1.0
After Improvements:
- Rental increase of 8{b92bc4f90207b85c6e672c12389678840946188ba238ac1c1570ae4bcd8b3d52} (+$192)
- Insurance savings of $40/month
- Property tax appeal saving $50/month
- Additional 5{b92bc4f90207b85c6e672c12389678840946188ba238ac1c1570ae4bcd8b3d52} down payment reducing loan by $20,000 (saving $100/month)
New Scenario:
- Monthly PITIA: $2,210
- Monthly Rental Income: $2,592
- Improved DSCR: 1.17
This improvement from 1.0 to 1.17 could mean the difference between loan denial and approval, or between standard rates and premium terms.
DSCR Improvement as an Ongoing Strategy
Improving your DSCR isn’t just about qualifying for a particular loan—it’s about creating stronger, more resilient investment properties. The strategies outlined here serve dual purposes: they help you secure better financing while simultaneously improving your real investment returns.
As we emphasized in our DSCR Loans 101 article, understanding the metrics that matter to lenders helps you think like a sophisticated investor. By focusing on DSCR improvement, you’re aligning your investment strategy with proven principles of successful real estate investing: maximizing income, controlling expenses, and optimizing financing.
Whether you’re applying for your first DSCR loan or managing an extensive portfolio, these seven strategies provide a roadmap for stronger property performance and better financing options. Implement them consistently, and you’ll not only improve your DSCR—you’ll build a more profitable and sustainable real estate investment business.
Ready to improve your DSCR Ratio and put these strategies into action? Start by analyzing your current or prospective properties using our DSCR calculation approach outlined in the previous article, then systematically apply these improvement techniques where they’ll have the greatest impact.